Expectation
Definition
For an integrable real-valued random variable , its expectation is the probability-weighted mean. The formulas are
Finite expectation requires : respectively or . More generally, write with positive part and negative part ; the extended expectation is defined if at least one of and is finite. If both are infinite, is undefined.
Interpretation
Expectation describes the centre of a distribution by weighting each outcome by its probability. Sums and integrals express the same idea for discrete variables and variables with densities.
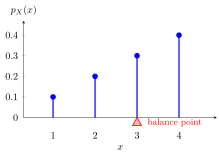
For the illustrated masses, the mean is . This probability-weighted average is the balance point of the masses and the long-run average of i.i.d. draws.
Treat the probabilities as weights on a seesaw and move the fulcrum : it balances exactly at .
For a discrete variable, the probability mass function supplies the weight attached to each possible value in the expectation sum. These are probability weights, not equal weights unless the distribution is uniform.
Key Results
- For nonnegative , expectation is well-defined in , even when it is not finite.
- For , , possibly .
Examples
- For a fair die, .
- If for and zero elsewhere, then .
Prerequisites
Related Concepts
- Infinite Series
- Distribution
- Discrete Random Variable
- Survivor Function
- Indicator Random Variable
- Poisson Distribution
- Sample Mean
Sources
- Probability Theory for EOR · Week 4
- Nicky van Foreest · Probability Distributions · Refresher
- Nicky van Foreest · Probability Distributions · Refresher
Aliases: expected value, expectation value, mathematical expectation, population mean Keywords: mean, first moment, average, Expectation of a Discrete Random Variable, Expectation of a Continuous Random Variable Symbols: infinity, integral, real numbers, sum
Last updated: 22 October 2026 19:04
ExpectationConditional Expectation Given an EventFundamental BridgeLinearity of ExpectationLOTUSMonotonicity of ExpectationStandardizationVariance and Standard DeviationChebyshev InequalityConditional Expectation Given a Random VariableGeneralized Markov InequalityJensen InequalityTwo-Dimensional LOTUS for Continuous VariablesTwo-Dimensional LOTUS for Discrete VariablesMomentStrong Law of Large NumbersActuarial Present ValueComplete and Curtate Expectation of LifeBayesian GameExpected Payoff MaximizationRevenue Equivalence TheoremExpected Utility and Risk AversionExponential FamilyPremium Principles and Their PropertiesProbability Generating FunctionStop-Loss Transform and ReinsuranceRandom VariableProbability Mass FunctionProbability Density FunctionInfinite SeriesDistributionDiscrete Random VariableSurvivor FunctionIndicator Random VariablePoisson DistributionSample Mean