Probability Density Function
Definition
A probability density function of an absolutely continuous is a nonnegative integrable function satisfying
Densities that agree except possibly on a set of zero length, for example at finitely many points, describe the same distribution. This qualification is called almost everywhere here: values on the exceptional set do not affect the integrals. It does not require two densities to agree at every point.
Interpretation
A density describes how probability is spread over the real line: probabilities are areas under its graph, not heights.
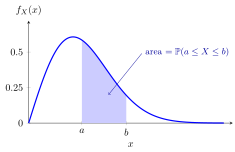
The shaded region between and has area , the first formula of the Definition with , and the whole area under the curve is . Moving to the right adds the area of a thin strip. A strip of zero width has zero area, so and it does not matter whether the endpoints are included.
Probabilities are areas under the density. The narrow uniform density reaches height , which is fine: only areas, never heights, are probabilities.
The height is probability per unit length. For a short interval of length starting at a point where is continuous, . This is why a height above is allowed, as for the uniform density of height on , and why changing at finitely many points changes no probability: no area changes. The definite integral measures these areas; for the piecewise continuous densities in the examples, Riemann integral calculations evaluate them.
For a continuous random variable the density plays the role that the PMF plays for a discrete one, with sums replaced by integrals. Integrating the density up to gives the CDF, and by the fundamental theorem of calculus differentiating the CDF gives back at every point where is continuous. Density height itself is never a point probability.
Key Results
- .
- , so except possibly on a set of zero length.
Examples
- For on and zero elsewhere, .
- The uniform density on has height , total area , and .
Prerequisites
Related Concepts
- Cumulative Distribution Function
- Derivative and Differentiability
- Support of a Random Variable
- LOTUS
Sources
- Probability Theory for EOR · Week 5
- Nicky van Foreest · Probability Distributions · Refresher
Aliases: PDF, density function, probability density, p.d.f. Keywords: density Symbols: element of, infinity, integral, real numbers
Last updated: 20 October 2026 03:02
Probability Density FunctionExpectationExponential DistributionModeNormal DistributionTransformation of a Continuous Random VariableUniform DistributionConditional Density Given an EventConvolution of Independent Random VariablesDensity of an Order StatisticGamma DistributionJoint Probability Density FunctionForce of MortalityExpected Payoff MaximizationExponential FamilyMaximum Likelihood EstimationCrossing Criteria for Risk OrdersAbsolutely Continuous DistributionContinuous Random VariableDefinite IntegralRiemann IntegralCumulative Distribution FunctionDerivative and DifferentiabilitySupport of a Random VariableLOTUS