Independent Random Variables
Definition
Real-valued random variables and are independent if
for every pair of intervals ; equivalently, for every pair of Borel sets . For a finite family, mutual independence requires the analogous product formula for every selection of intervals (one for each variable) and every subfamily, rather than merely for pairs.
For discrete variables with a joint PMF, this is equivalent to for every . For a pair with a joint density, it is equivalent to for all except possibly on a set of zero area, for example along finitely many lines. In either case, conditional laws agree with the corresponding marginal laws wherever the conditioning denominator is positive (with density identities allowed to fail on a set of zero length or area).
Interpretation
Independent variables supply separate sources of randomness: learning one variable does not change the distribution of the other. PMF and PDF factorization are two ways to check the same property.
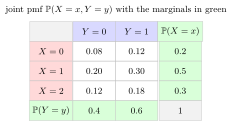
Every cell is the product of its row and column marginal, e.g. : and are independent, for all ; knowing does not change the distribution of .
The threshold events generated by the variables must be independent events for every selection of thresholds. This condition factors the joint law, rather than comparing only the marginal distributions or one pair of events.
Key Results
- For arbitrary real-valued , independence is equivalent to for every .
- If are independent and integrable, then is integrable and .
Examples
- Two independent fair dice have for all .
- The joint density on has marginals and on . At their product is , rather than , and this discrepancy persists on a whole neighbourhood, which has positive area; hence the density does not factor.
Prerequisites
Related Concepts
- Variance and Standard Deviation
- Conditional Probability Mass Function
- Joint CDF of Discrete Random Variables
- Conditional Probability Density Function
- Covariance
- Joint CDF of Continuous Random Variables
- Conditional Cumulative Distribution Function
- Correlation
- Joint Probability Mass Function
- Marginal Probability Mass Function
- Joint Probability Density Function
- Marginal Probability Density Function
- Binomial Distribution
Sources
- Probability Theory for EOR · Week 3
- Nicky van Foreest · Probability Distributions · Week 1
- Nicky van Foreest · Probability Distributions · Week 2
Aliases: independent r.v.s, independence of random variables, statistically independent random variables Keywords: independent variables, Independence of Discrete Random Variables, Independence of Continuous Random Variables Symbols: element of
Last updated: 22 October 2026 19:04
Independent Random VariablesFirst Success DistributionGeometric DistributionIndependent and Identically Distributed Random VariablesMinimum of Independent ExponentialsNegative Binomial DistributionPoisson ProcessSum of Independent Random VariablesChicken–Egg TheoremConditional Expectation and IndependenceConvolution of Independent Random VariablesMGF of an Independent SumPoisson MergingUniform Distribution of DeathsCollective Risk ModelIndividual Risk ModelMaximum Likelihood EstimationRandom VariableIndependent EventsDistributionVariance and Standard DeviationConditional Probability Mass FunctionJoint CDF of Discrete Random VariablesConditional Probability Density FunctionCovarianceJoint CDF of Continuous Random VariablesConditional Cumulative Distribution FunctionCorrelationJoint Probability Mass FunctionMarginal Probability Mass FunctionJoint Probability Density FunctionMarginal Probability Density FunctionBinomial Distribution