Critical Ratio
Definition
For newsvendor selling price , unit cost and salvage value , with overage cost and underage cost , the critical ratio is
It is the cumulative-demand probability used to select the optimal stock quantile.
Interpretation
The critical ratio turns the two newsvendor costs into a target cumulative-demand probability . It compares what one unit too few costs, the underage cost , with what one unit too many costs, the overage cost . For a continuous strictly increasing CDF, the optimal stock satisfies . For discrete demand, the CDF can jump past this target.
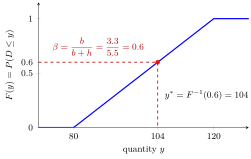
The CDF gives the probability that demand is at most . For meals, ; reading across from height to the CDF and then down gives , the quantity that covers demand with probability .
The ratio comes from the last unit ordered. It is unsold with probability , costing , and sold with probability , saving , so ordering it pays while , that is, while . A large underage cost pushes towards and the stock up; a large overage cost pushes towards . The second form follows from and shows the prices directly: a higher selling price or a higher salvage value raises , and a higher unit cost lowers it. How far the price can move before the order changes is the subject of newsvendor price sensitivity.
A common slip is to read as the fraction of demand that is served on average. The actual probability that all demand is met is , which equals the target in the continuous examples but need not equal it for discrete demand. For example, if demand is or with equal probabilities and , the optimal integer stock is and covers all demand with probability .
Key Results
- For integer demand, increasing from to helps while .
- For the continuous strictly increasing CDFs used in the examples, the optimum solves .
- The ratio is not the expected fraction of demand served.
Examples
- Newspapers with and have .
- Meals with and have .
Prerequisites
- Overage Cost
- Underage Cost
- Cumulative distribution functions
Related Concepts
Sources
- OR Modelling · Week 6
Aliases: Critical fractile Symbols: beta
Last updated: 27 October 2026 11:52
Critical RatioContinuous Newsvendor RuleDiscrete Newsvendor RuleOverage CostUnderage Cost