Diagonalizable Matrix
Definition
Over a chosen field (here or ), a square matrix is diagonalizable if there exists an invertible matrix such that is diagonal, with and both having entries in .
A square matrix without an eigenbasis over is non-diagonalizable over . When its characteristic polynomial splits into linear factors over that field, it is called defective if it does not have enough linearly independent eigenvectors to form an eigenbasis. Jordan normal form is the tool used for such defective matrices over a field in which the characteristic polynomial splits. For example, a real planar rotation can fail to be diagonalizable over while being diagonalizable over ; this is not defectiveness.
Interpretation
A diagonalizable matrix becomes diagonal after changing to a suitable basis. A diagonal matrix only scales each coordinate; a diagonalizable matrix does the same once coordinates are measured along its eigenvectors.
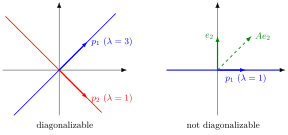
On the left, has two independent eigenvectors, for the eigenvalue and for the eigenvalue . With these as the columns of , . On the right, the shear has the double eigenvalue , but all its eigenvectors lie on the horizontal axis: is sent to , off its own line. One direction is too few for a basis of , so the shear is not diagonalizable.
Being diagonalizable is the same as having an eigenbasis: the columns of are eigenvectors, and the diagonal of holds their eigenvalues. In terms of the multiplicities, every eigenvalue needs ; the shear fails with and . Having distinct eigenvalues is a sufficient shortcut, but not a necessary one, as shows. The field matters too: the quarter-turn rotation has no real eigenvalues, so it is not diagonalizable over , but it is diagonalizable over , with eigenvalues .
Diagonalization finds and the diagonal matrix; where it fails, Jordan normal form is the nearest substitute.
Diagonalizable and invertible are unrelated properties. The diagonal matrix is diagonalizable but singular, and the shear is invertible, with determinant , but not diagonalizable.
Key Results
- A matrix is diagonalizable if it has enough linearly independent eigenvectors to form a basis.
- If an matrix has distinct eigenvalues in , it is diagonalizable.
Examples
- Every diagonal matrix is diagonalizable.
- is not diagonalizable.
Prerequisites
Related Concepts
- Jordan Normal Form
- Algebraic and Geometric Multiplicity
- Diagonalization
- Basis
- Inverse and Singular Matrices
Sources
- Math II: Linear Algebra · Week 6
Aliases: diagonalisable matrix, diagonalizable, diagonalisable Keywords: defective matrix, non-diagonalizable matrix Symbols: complex numbers, real numbers
Last updated: 20 October 2026 03:02
Diagonalizable MatrixMatrixEigenvalue and EigenvectorEigenbasisJordan Normal FormAlgebraic and Geometric MultiplicityDiagonalizationBasisInverse and Singular Matrices