Chebyshev Inequality
Theorem
For with finite variance , mean , and any ,
Bounds can be capped at . If , then almost surely and the deviation probability is zero.
The Inequality bounds a tail probability from above; it is not an equality or an approximation. Applying the Markov inequality to the nonnegative squared deviation gives this bound.
Interpretation
Finite variance guarantees a bound on how often a variable can be far from its mean, regardless of the shape of the distribution. Measured in standard deviations, at most of the probability lies or more from : at most beyond and at most beyond .
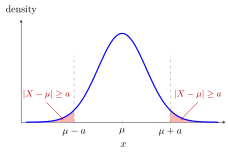
The figure shades both tails beyond of a normal density with . Chebyshev's inequality bounds the combined shaded probability by , while for the normal distribution it is approximately . The bound is loose here because it must hold for every distribution with the same variance.
The proof applies the Markov inequality to , so only the variance enters: no symmetry, single peak or density is assumed. The bound is informative only for ; for the right-hand side is at least . Although it is loose for the normal distribution, it cannot be improved in general: if and takes the values and with probability each and otherwise, then has variance and exactly.
Its main use is the weak law of large numbers. The sample mean of i.i.d. observations has variance , so , which tends to for every fixed : this is convergence in probability of to .
Key Results
- If and , .
- Applying the Markov inequality to with threshold proves the bound .
Examples
- For mean , standard deviation , and deviation threshold , the probability is at most .
- For an i.i.d. sample with variance , , giving at .
Prerequisites
Related Concepts
- Convergence in Probability
- Absolute Value
- Generalized Markov Inequality
- Chernoff Bound
- Almost Surely
Sources
- Nicky van Foreest · Probability Distributions · Week 7
Aliases: Chebyshev's inequality, Bienaymé-Chebyshev inequality, Tchebysheff's inequality, Chebyshev's bound Symbols: epsilon, mu, sigma
Last updated: 20 October 2026 03:02
Chebyshev InequalityWeak Law of Large NumbersVariance and Standard DeviationExpectationInequalityConvergence in ProbabilityAbsolute ValueGeneralized Markov InequalityChernoff BoundAlmost Surely