Joint CDF of Discrete Random Variables
Definition
The joint CDF of a random pair is
The definition applies to any random pair; this page develops its discrete form, and Joint CDF of Continuous Random Variables develops the form with a joint density.
Interpretation
The joint CDF measures the probability that two variables simultaneously lie below specified thresholds: is the probability that is at most and is at most . For a discrete pair it is the sum of the joint masses in the lower-left corner below .
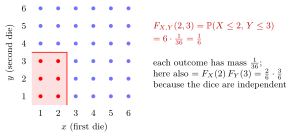
For two fair dice the highlighted corner contains of the equally likely outcomes, so . Because the dice are independent, this also equals .
The joint CDF is defined at every point of the plane, not only at possible values. Between possible values it is constant, so for the dice . It is nondecreasing in each argument, and letting removes the condition on and leaves the CDF of . In general the joint CDF is not the product of the two marginal CDFs; it is for independent variables. For , , not .
Probabilities of rectangles follow from four corner values by inclusion–exclusion: for and ,
For the dice, . The joint CDF of continuous variables has the same definition, with the sum replaced by an integral of a joint density.
Key Results
- .
- and similarly for .
Examples
- For independent fair dice, .
- If is Bernoulli with parameter , then , rather than .
Prerequisites
Related Concepts
- Joint Probability Mass Function
- Independent Random Variables
- Joint CDF of Continuous Random Variables
Sources
- Nicky van Foreest · Probability Distributions · Week 1
Keywords: joint CDF, joint distribution function Symbols: infinity, sum
Last updated: 20 October 2026 03:02
Joint CDF of Discrete Random VariablesCumulative Distribution FunctionJoint Probability Mass FunctionIndependent Random VariablesJoint CDF of Continuous Random Variables