Dutch Auction
Definition
In a Dutch auction the price starts high and falls continuously (for example on a clock). The first bidder to stop the clock wins the object and pays the current price; the auction then ends. A strategy specifies, for each valuation , the price at which the bidder will stop the clock if nobody has stopped it before.
The Dutch auction is strategically equivalent to the first-price auction: the two games have the same strategy sets (a planned stopping price is a bid) and the same mapping from strategy profiles to outcomes (the highest planned price wins and is paid).
Interpretation
The equivalence is easiest to see by writing the Dutch auction as a normal-form game. A strategy in an extensive-form game must say what to do at every point where the bidder could act. But the only information a bidder ever receives before the auction ends is that no one has stopped yet; once someone stops, the auction is over. So a complete plan reduces to one number: the price at which to stop. Bidder planning to stop at wins if and only if is the highest planned stopping price, and then pays . That is exactly the first-price sealed-bid rule.
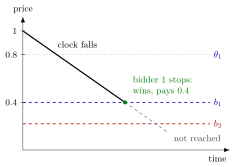
In the figure the clock falls from . Bidder 1, with , plans to stop at , the two-bidder equilibrium of the Examples; bidder 2 plans to stop at , drawn here below . The clock reaches the higher planned price first, so bidder 1 wins and pays , and the lower plan is never reached. Read the two dashed lines as sealed bids and the outcome is the same: the highest bid wins and its bidder pays it.
As a result the Dutch auction has the same equilibria as the first-price auction. With values i.i.d. , the symmetric equilibrium stops the clock at . The bidder faces the same trade-off as in a sealed first-price bid: waiting lowers the price paid but raises the risk that a rival stops first.
Unlike the English–second-price equivalence, the Dutch–first-price equivalence does not require private values. Because no rival's action is observed during a Dutch auction until it ends, the equivalence also holds with common values or risk-averse bidders.
Key Results
- The Dutch and first-price sealed-bid auctions are strategically equivalent under any assumptions on values and risk attitudes.
- With i.i.d. private values and risk-neutral bidders, the symmetric equilibrium stopping price is and expected revenue is .
- There is no weakly dominant stopping rule: the best stopping price depends on the rivals' stopping prices.
- Under the conditions of the revenue equivalence theorem, the Dutch auction gives the same expected revenue as the English and second-price auctions.
Examples
Two bidders. Values are i.i.d. and both use the first-price equilibrium as stopping rule. A bidder with stops the clock at . She wins if the rival's stopping price is below , i.e. with probability , and expects .
Waiting longer. If she instead plans to stop at , she wins with probability and expects . Stopping earlier, at , gives as well.
Prerequisites
Related Concepts
Sources
- Game Theory · Week 6
Aliases: descending auction, descending-price auction, descending clock auction, open descending auction Keywords: descending clock, clock auction, strategic equivalence with first-price auction, stop the clock Symbols: theta
Last updated: 27 October 2026 11:52
Dutch AuctionFirst-Price AuctionNormal-Form GameStrategy in an Extensive-Form GameEnglish AuctionSecond-Price AuctionRevenue Equivalence TheoremCommon-Value Auction