Expected Utility and Risk Aversion
Definition
The expected utility model compares uncertain wealth through . An increasing concave utility function represents risk aversion: for integrable wealth with well-defined utilities, . A linear increasing utility represents risk neutrality.
Interpretation
A risk-averse policyholder can prefer a fixed payment to an uncertain loss with the same mean. Utility is applied to final wealth, so larger losses usually reduce utility.
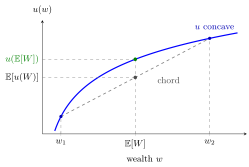
The figure, drawn schematically, takes wealth equal to or with probability each. The expected utility is the midpoint of the dashed chord, while is the height of the curve at the mean; concavity keeps the curve above the chord, so . In the Example , and under logarithmic utility: , so the certain loss of 10 is preferred.
Choose a utility and move the wealth , the loss and its probability: the chord value stays below , and the horizontal gap to the certainty equivalent is the risk premium. The default logarithmic case gives .
Convexity and concavity describes the downward curvature of a risk-averse utility. Applying Jensen's inequality to this concave function gives , the comparison between uncertain wealth and its certain mean.
Key Results
- Replacing by with preserves preferences.
- Concavity gives the Jensen comparison; strict preference requires suitable strict concavity and nondegenerate wealth.
- Fractional power utility requires positive wealth. Quadratic utility is increasing only on a restricted domain.
- The expected value of a payoff and expected utility are different criteria.
Examples
At wealth 100, a loss of 0 or 20 with equal probabilities gives expected logarithmic utility . A certain loss of 10 gives , which is larger.
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 7
Aliases: utility of wealth, risk-averse decision maker, expected utility model, expected utility theory, risk aversion, expected utility hypothesis, risk-averse Keywords: risk neutrality, concave utility, E[u(W)] ≤ u(E[W]), Jensen's inequality for utility, logarithmic utility, certainty equivalent
Last updated: 17 October 2026 21:53
Expected Utility and Risk AversionAbsolute Risk AversionInsurance Indifference PremiumsSecond-Order Stochastic DominanceJensen InequalityExpectationConvexity and ConcavityConvex Order and More Dangerous Risks