Exponential Premium Principle
Definition
For risk-aversion parameter and loss with , the exponential premium is .
Interpretation
This is the indifference price for exponential wealth utility. It gives extra weight to large losses and may be infinite for losses whose positive exponential moments do not exist.
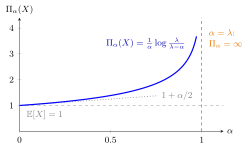
The figure draws the Examples formula with , so and . The premium never falls below , as Jensen's inequality requires; near it follows the dotted approximation ; and as approaches the moment blows up, so the premium is infinite for .
Move towards : grows without bound and is infinite for , while near it follows .
The cumulant generating function is the logarithm of the loss moment generating function (MGF), so expresses the premium compactly. In insurance indifference premiums, substituting exponential wealth utility into the insurer's equation and cancelling the wealth factor gives precisely this formula.
Key Results
- Jensen's inequality gives .
- Translation consistency and independent additivity follow from exponential products.
- Iterativity follows from the tower property: .
- It respects exponential order and hence stop-loss order.
- For bounded , .
- Near with sufficient moments and a finite MGF, .
Examples
For exponential severity of rate and , premium is . At or above it is infinite.
Prerequisites
Related Concepts
- Exponential Order
- Zero-Utility Premium
- Absolute Risk Aversion
- Expected Value Premium Principle
- Pareto Loss Model
- Premium Principles and Their Properties
Sources
- Risk Insurance · Lecture 12
Aliases: entropic premium, exponential utility premium, exponential principle, exponential premium Keywords: Π_α(X) = (1/α) log E[e^(αX)], risk-aversion parameter α, E[X] + α Var(X)/2, zero-utility premium with exponential utility, infinite premium for heavy tails Symbols: alpha, infinity, lambda, pi
Last updated: 16 October 2026 22:28
Exponential Premium PrincipleCumulant Generating FunctionInsurance Indifference PremiumsExponential OrderZero-Utility PremiumAbsolute Risk AversionExpected Value Premium PrinciplePareto Loss ModelPremium Principles and Their Properties