Exponential Order
Definition
For nonnegative losses, exponential order means for every . Comparisons may use extended values, but a finite exponential premium at a given requires the corresponding moment to be finite.
Interpretation
The comparison tests every exponential risk-aversion parameter. It is weaker than agreement among all increasing concave wealth utilities.
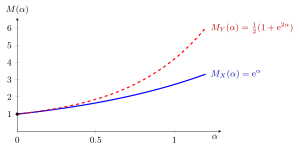
The figure plots the two moment generating functions of the Examples case. Both curves start at 1 when with the same slope, because and have the same mean 1; for every the curve of lies above that of , which is exactly . The gap widens as grows, because a larger risk-aversion parameter weights the outcome 2 of more heavily.
Move : at every , so , and the exponential premium of is the larger one. Shrink the spread to 0 and the two curves coincide.
The moment generating function evaluates . Exponential order compares these values over positive arguments; finiteness at the chosen argument is needed when turning the comparison into a finite premium.
Key Results
- Stop-loss order implies exponential order, since is increasing and convex.
- For , exponential order gives the reverse order of expected utilities of and .
- With equal means and MGFs finite near zero, a Taylor comparison gives .
- If both positive MGFs are infinite, the comparison can carry little information about finite premiums.
Examples
For and equal 0 or 2 with probability , for every positive .
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 10
Aliases: MGF order for positive arguments, exponential utility risk ordering, exponential ordering Keywords: X ≤_e Y, E[e^(αX)] ≤ E[e^(αY)], comparison of moment generating functions, stop-loss order implies exponential order Symbols: alpha
Last updated: 16 October 2026 22:28
Exponential OrderRisk Orders Under AggregationMoment Generating FunctionStop-Loss OrderExponential Premium Principle