Cumulant Generating Function
Definition
If the moment generating function (MGF) is finite in a neighbourhood of zero, the cumulant generating function is on that domain. Its derivatives at zero are called cumulants.
Interpretation
Taking logarithms turns products of independent MGFs into sums. This makes cumulants a convenient way to describe aggregate risk.
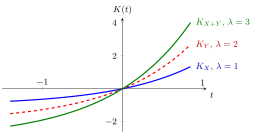
The figure plots the Example's for independent and (rates chosen for the figure) and for . At every the green curve is the sum of the blue and red ones, which is the additivity . All three pass through the origin because , and their slopes there are , and , the means .
Change the two Poisson means and move : at every , so is Poisson with mean , and the first two derivatives at 0 both equal the mean.
The MGF of an independent sum is the product of the component MGFs. Taking its logarithm converts that product into addition, which explains the additive cumulant formula.
Key Results
- and .
- For independent with suitable MGFs, .
- for constants on the common domain.
- Existence of ordinary moments does not ensure a finite MGF for positive arguments.
Examples
For , . Its first two derivatives at zero both equal .
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 1
Aliases: CGF, log moment generating function, cumulant-generating function, log-MGF Keywords: K_X(t) = log M_X(t), cumulants, K'(0) = E[X], K''(0) = Var(X), additivity for independent sums, Poisson CGF λ(e^t - 1) Symbols: lambda
Last updated: 17 October 2026 21:53
Cumulant Generating FunctionExponential Premium PrincipleMoment Generating FunctionMGF of an Independent SumCompound Poisson DistributionProbability Generating Function