Standard Deviation Premium Principle
Definition
For a loss with finite second moment, the standard deviation principle sets , with dimensionless fixed loading .
Interpretation
The loading is measured in the same monetary units as loss. Independent pooling generally gives a smaller loading than adding the separate standard deviation loadings.
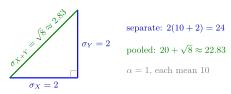
For independent risks the variances add, so the standard deviations combine like the two legs of a right triangle: in the Examples case the pooled is the hypotenuse, shorter than the path along the legs. At the total loading therefore falls from 4 to about 2.83, and the premium from 24 to about 22.83; this diversification effect is why the principle is not additive.
Change , and : for independent risks the pooled loading is the hypotenuse of the triangle, never longer than the separate loadings .
Key Results
- It has nonnegative loading, translation consistency and proportionality for positive scaling.
- For independent losses, .
- Therefore it is generally not additive, and it rewards diversification.
- Equal-mean convex order raises the premium when second moments are finite; stochastic order alone need not do so.
Examples
Two independent risks each have mean 10 and standard deviation 2. At , separate premiums sum to 24, while the pooled premium is .
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 12
Aliases: standard deviation loading, SD premium principle, standard deviation principle Keywords: Π(X) = E[X] + α √Var(X), diversification, not additive, σ_{X+Y} ≤ σ_X + σ_Y Symbols: alpha, pi, sigma, square root
Last updated: 14 October 2026 08:21
Standard Deviation Premium PrinciplePremium Principles and Their PropertiesVariance and Standard DeviationVariance Premium PrincipleConvex Order and More Dangerous Risks