Second-Order Stochastic Dominance
Definition
For nonnegative integrable gain or wealth variables , has second-order stochastic dominance over if for every . Equivalently, every increasing concave utility weakly prefers to , with expectations defined.
Interpretation
This comparison is stated for favourable outcomes. When the variables denote losses, put the minus sign inside wealth utility. A larger mean alone does not establish second-order dominance.
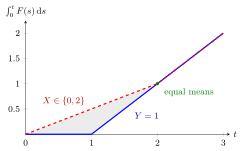
The figure reads the Examples case as gains: is the fair draw of 0 or 2 and is certain. Then for , while there; the shaded gap shows that the first integral is never below the second, which is the definition of dominating in second order. From on both integrals equal , because once exceeds every outcome the integral equals minus the mean, and the means are equal.
Move the certain gain and the spread of : while the integrated CDF of is never below that of , so the certain gain dominates. Push below 1 and the curves cross.
Convex order and more dangerous risks compares dispersion at equal means. In that case makes every concave utility prefer the gain , explaining the direction of the equal-mean second-order comparison.
Key Results
- First-order dominance of over implies second-order dominance.
- Dominance requires for integrable variables.
- At equal means, dominating in second order corresponds to .
- For losses, corresponds to preference for wealth over by increasing concave utility.
Examples
As gains, a certain 1 second-order dominates a fair draw of 0 or 2. As losses, the same certain 1 is the less dangerous risk. The preference direction is the same after the outcome meaning is specified.
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 10
Aliases: increasing concave order, second-order dominance of wealth, SSD, second-order dominance, second-degree stochastic dominance Keywords: integrated CDF, increasing concave utility, ∫_0^t F_X(s) ds ≥ ∫_0^t F_Y(s) ds, risk-averse preference, gains versus losses Symbols: integral
Last updated: 17 October 2026 21:53
Second-Order Stochastic DominanceExpected Utility and Risk AversionConvex Order and More Dangerous RisksStochastic OrderStop-Loss Order