Probability Generating Function
Definition
For a nonnegative integer-valued random variable , its probability generating function (PGF) is , at least for . In this power-series definition , including at .
Interpretation
The coefficient of each power stores a probability. PGFs are especially useful for counting claims and for composing claim frequency with claim severity.
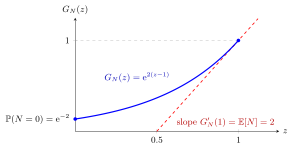
Here with , so . The height at is the constant coefficient, , and the curve ends at because the probabilities sum to one. The dashed tangent at has slope , the mean read off by differentiating at one.
Pick a count law and move : , the slope at is and the power-series coefficients are the probabilities shown on the right. The default gives and .
For a discrete random variable taking nonnegative integer values, expectation becomes a sum of weighted by the count probabilities. Substituting connects the PGF with the moment generating function wherever the transform is finite.
Key Results
- .
- and , allowing infinite values.
- Independent nonnegative integer-valued sums have product PGFs.
- For where finite, . A general real-valued severity need not have a PGF.
Examples
For , . Differentiating at one gives mean and second factorial moment .
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 1
Aliases: PGF, probability generating transform, probability-generating function Keywords: G_N(z) = E[z^N], P(N = k) = G_N^(k)(0)/k!, factorial moments, Poisson PGF e^(λ(z - 1)) Symbols: infinity, lambda, sum
Last updated: 14 October 2026 08:21
Probability Generating FunctionCompound Risk DistributionMaximum Claim in a PortfolioMoment Generating FunctionDiscrete Random VariableExpectationCumulant Generating FunctionPoisson Distribution