Convolution of Independent Random Variables
Theorem
For independent continuous random variables and , the density of is the convolution of their densities; independence is what lets the joint density factor into the two marginal densities:
Interpretation
A sum can reach a value in many ways. For to be near , takes some value and must take the matching value ; convolution adds up all these splits, each weighted by .
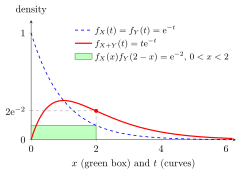
For independent , the product is constant for , so the green region is a rectangle of height and width . Its area is the height of the red point. More generally, for .
Move : is flipped and shifted, and the area of its product with is , traced on the right.
Independence is what turns the joint density into the product . Without it the formula fails: for and , the sum is uniform on with density , whereas the convolution of two uniform densities gives the triangular density. The integral only runs over the for which both factors are positive, which for exponentials is .
The discrete version is the sum used for two dice in Probability Theory (sum of independent random variables). Moment generating functions give a second route: by the MGF of an independent sum, , which avoids the integral when the product is a recognizable MGF. The density found here is the Gamma distribution with shape and rate .
Adding values is not adding densities: has total integral , and the product is not a density of the sum either.
Key Results
- For independent discrete variables, .
- For independent variables with densities, the integral is over for which both density factors are nonzero.
Examples
- For independent variables, for .
- For independent fair Bernoulli variables, the sum has masses at .
Prerequisites
Related Concepts
Sources
- Nicky van Foreest · Probability Distributions · Week 3
Aliases: convolution formula, convolution integral Symbols: integral, sum
Last updated: 20 October 2026 03:02
Convolution of Independent Random VariablesSum of Two IID Uniform VariablesCompound Risk DistributionIndividual Risk ModelProbability Density FunctionIndependent Random VariablesMGF of an Independent SumGamma DistributionTransformation of a Continuous Random Variable