Pareto Loss Model
Definition
The course's Pareto loss model has survivor function for , shape and scale . It is the Lomax or Pareto type II convention, whose support starts at zero; an unshifted Pareto type I model has a different support.
Interpretation
The polynomial tail allows occasional very large losses. The shape controls which moments are finite, so a valid loss distribution need not have finite variance.
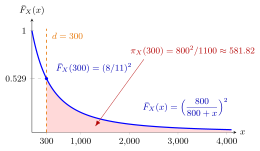
With and , the survivor function falls only like , so a visible share of probability remains far to the right. The total area under is . The red area beyond the deductible is the stop-loss transform , the mean excess per loss; dividing by gives the mean excess per payment, . Because the tail is so heavy, part of the red area lies beyond the plotted range.
The ordinary deductible separates per-loss excess from excess conditional on a payment. The Pareto survivor ratio above gives a conditional excess law with scale , while integrating the tail gives the expected payment per ground-up loss.
Key Results
- for .
- for ; variance is for .
- For , the stop-loss transform is .
- Conditional excess over is Lomax with the same shape and scale .
- Every positive exponential moment is infinite, so an exponential premium is infinite.
Examples
With , and deductible 300, mean ground-up loss is 800 but variance is infinite. Mean excess per loss is , and mean excess per payment is 1100.
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 2
Aliases: Lomax distribution, Pareto type II, shifted Pareto distribution, Pareto distribution, Lomax, Pareto II Keywords: heavy tail, survivor function (β/(β + x))^α, mean excess (β + d)/(α - 1), infinite variance, infinite exponential premium Symbols: alpha, beta, pi
Last updated: 17 October 2026 21:53
Pareto Loss ModelSurvivor FunctionOrdinary DeductibleStop-Loss Transform and ReinsuranceExponential Premium Principle