Ordinary Deductible
Definition
For a nonnegative ground-up loss (the full loss before any deductible or limit is applied) and deductible , the insurer's per-loss payment is . The insured retains . The per-payment distribution is the conditional law of given (written ), defined only when .
Interpretation
Every loss is included in the per-loss model, with a zero payment below the deductible. The per-payment model describes only cases generating a positive payment.
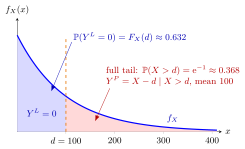
For and , the blue area is : these losses stay in the per-loss model with payment zero. The red area holds the losses that produce a payment ; rescaling that tail by gives the per-payment law , which here is again exponential with mean 100. Hence , as in the example.
The survivor function gives the probability that the deductible is exceeded. Dividing the shifted tail by this probability normalizes the per-payment law over cases receiving a positive payment.
Key Results
- and for .
- For , .
- when finite.
- For continuous , for .
Examples
For and , the probability of payment is . By the memoryless property, conditional payment has mean 100, so mean payment per loss is .
Prerequisites
Related Concepts
- Stop-Loss Transform and Reinsurance
- Franchise Deductible
- Loss Elimination Ratio
- Hunger for Bonus
- Mixed Discrete and Continuous Loss Distribution
Sources
- Risk Insurance · Lecture 1
Aliases: excess deductible, per-loss deductible payment, straight deductible Keywords: (X - d)+, per-loss variable Y^L, per-payment variable Y^P, ground-up loss, memoryless exponential deductible
Last updated: 16 October 2026 22:28
Ordinary DeductibleCoinsuranceFranchise DeductibleLoss Elimination RatioPareto Loss ModelPolicy LimitStop-Loss Transform and ReinsuranceLikelihood for Truncated Loss DataSurvivor FunctionConditional ProbabilityHunger for BonusMixed Discrete and Continuous Loss Distribution