Expected Value Premium Principle
Definition
For integrable loss , the expected value principle sets , where is a fixed loading coefficient: the loading is a fixed proportion of the mean, so the principle has nonnegative loading. At , it is the net premium principle, .
Interpretation
The loading is a constant proportion of expected loss. Different risks with the same mean receive the same price, regardless of their dispersion.
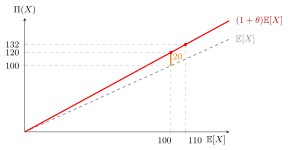
The figure draws the Examples case . The premium line is a ray through the origin with slope , so the loading, the vertical gap to the net-premium line , grows in proportion to the mean: at the premium is 120 and the gap is 20. Only the mean enters, so any two risks with that mean sit at the same point. Adding a certain 10 moves the mean to 110 and the premium to 132, so the certain amount is loaded as well, which is why translation consistency fails.
Key Results
- The principle is proportional and additive for integrable losses, even without independence.
- It has nonnegative loading and is monotone under stochastic or stop-loss order.
- For , translation consistency fails: adding certain cost adds to the premium.
- Iterativity follows from total expectation only in the net case; repeating a positive loading generally applies it twice.
Examples
For expected loss 100 and , premium is 120. Adding a certain 10 raises the premium to 132, rather than 130.
Prerequisites
Related Concepts
- Variance Premium Principle
- Exponential Premium Principle
- Actuarial Present Value
- Zero-Utility Premium
Sources
- Risk Insurance · Lecture 11
Aliases: mean loading principle, expected value principle, expected-value premium principle Keywords: net risk premium, net premium principle, Π(X) = (1 + θ) E[X], loading coefficient θ, proportional loading Symbols: pi, theta
Last updated: 14 October 2026 08:21
Expected Value Premium PrinciplePremium Principles and Their PropertiesVariance Premium PrincipleExponential Premium PrincipleActuarial Present ValueZero-Utility Premium