Actuarial Present Value
Definition
The actuarial present value (APV) of an insurance cash flow is the expectation of its random present value : , when integrable. For a benefit paid at death under constant force of interest , . Define and for annual effective interest .
Interpretation
The payment timing is uncertain even when the benefit amount is fixed. Discount each possible payment first, then average over the mortality model.
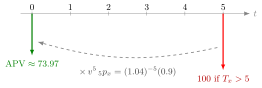
The figure uses the Examples case. The payment of 100 at time 5 is made only if ; carrying it back to time 0 multiplies it by the discount factor and by the survival probability . The result, , is the expectation of a present value that equals with probability and otherwise.
The future lifetime determines when a death benefit is paid. Its density weights the discounted benefit in the integral below; for a survival payment, the event determines whether that payment occurs.
Key Results
- A nonnegative benefit paid at death has APV .
- For payments at fixed times conditional on survival, APV is .
- Scaling benefits by scales APV by and variance by .
- A net single premium covers expected discounted benefits under the chosen basis; expenses and risk loading require additional treatment.
Examples
A payment of 100 at time 5 with survival probability and has APV .
Prerequisites
Related Concepts
Sources
- Life Insurance · Lecture 3
Aliases: APV, expected present value, net single premium, EPV, actuarial value, expected discounted value Keywords: expected discounted benefit, E[Z] of the random present value, discount then average over survival, discount factor v = 1/(1+i), force of interest delta = log(1+i) Symbols: delta, infinity, integral, sum
Last updated: 17 October 2026 21:53
Actuarial Present ValueAnnuity CertainFuture Loss Random VariableVariance of an Insurance Present ValueEquivalence Principle for Life Insurance PremiumsPure EndowmentWhole Life InsuranceFuture LifetimeExpectationInterest and DiscountingExpected Value Premium Principle