Temporary Life Annuity
Definition
A unit -year temporary life annuity pays while the life survives, for at most payments. For integer , the due version has payments at and the immediate version at .
Interpretation
The term limits payment duration even if the annuitant lives longer. The final immediate payment requires survival to time , whereas the due version starts with a certain payment at time zero.
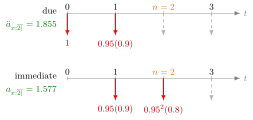
The figure uses the example values , , and . Each red arrow is a unit payment conditional on survival, labelled with its contribution to the actuarial present value (APV); the grey arrows are whole life payments that the term cuts off. The due version keeps the certain payment at time and stops before , giving ; the immediate version starts at time and includes the payment at , which needs survival to , giving . Their difference, , is .
Truncating the payment sum of a whole life annuity-due after times gives the due version. Truncating a whole life annuity-immediate after times gives the immediate version. The identity involving endowment insurance uses the same stopping time: an annual death-or-survival payment occurs at , and the discounted annuity payments before it form a finite geometric sum. Taking expectations yields , where and is the annual-settlement endowment APV.
Key Results
- and .
- .
- For , , where is annual-settlement endowment APV.
- The whole life annuity is the limit as the term increases, when finite.
Examples
For , , and , the due APV is and the immediate APV is .
Prerequisites
Related Concepts
Sources
- Life Insurance · Lecture 5
Aliases: n-year life annuity, temporary annuity due and immediate, temporary annuity, temporary life annuity-due, temporary life annuity-immediate Keywords: ä x:n angle, d ä x:n = 1 - A x:n, due minus immediate equals 1 - n E x, annuity for at most n years Symbols: sum
Last updated: 14 October 2026 08:21
Temporary Life AnnuityDeferred Life AnnuityWhole Life Annuity DueWhole Life Annuity ImmediateEndowment InsuranceContinuous Life AnnuityGuaranteed Life Annuity