Annuity Certain
Definition
An annuity certain makes specified payments independently of survival. For annual unit payments, the annuity-due pays at , whereas the annuity-immediate pays at . With annual discount factor at interest rate , their present values are and .
Interpretation
This is the deterministic building block for life annuities, such as the whole life annuity-due. The due/immediate distinction describes payment timing, not uncertainty.
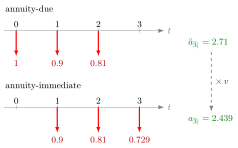
The figure uses the Examples case with and . Each red arrow is a unit payment, and the number below it is its present value . The annuity-due pays at times and is worth . The annuity-immediate makes the same three payments one year later, so every present value, and hence the total, is multiplied by : .
Because these payments are certain, their actuarial present value equals their ordinary discounted value. The geometric series formula evaluates the finite sums of powers of and gives the closed forms below.
Key Results
- With , and .
- A continuous unit-rate annuity has value , with limit at .
- Paying in advance every year gives .
- At positive interest, the infinite-duration versions () are called perpetuities, with and .
Examples
At , three unit payments in advance have value . Moving all payments one year later gives .
Prerequisites
Related Concepts
Sources
- Life Insurance · Lecture 4
Aliases: annuity due certain, annuity immediate certain, continuous annuity certain, certain annuity Keywords: perpetuity, present value of n level payments, (1 - v^n)/d, a angle n = v times ä angle n, geometric series of discount factors Symbols: delta, infinity, sum
Last updated: 14 October 2026 08:21
Annuity CertainGuaranteed Life AnnuityWhole Life Annuity DueActuarial Present ValueGeometric SeriesInterest and Discounting