Continuous Life Annuity
Definition
A continuous life annuity pays at rate one per year while the annuitant is alive. Its present value is , and its actuarial present value (APV) is . A temporary version stops at instead.
Interpretation
Continuous payments provide a tractable idealization of a frequent payment stream. Payment rate one means an amount over an interval of length , not a unit payment at every instant.
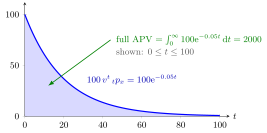
The figure uses the Examples values and . At time the benefit rate 100 is discounted by and is paid only if the annuitant is alive, which has probability , so the expected discounted rate is . The full integral to infinity is . The visible shading covers only , contributing ; the omitted tail contributes .
The whole life annuity-due values annual survival-contingent payments by a sum. Here a payment rate replaces those individual payments, so survival-weighted discount factors are integrated over time. The force of mortality determines ; a constant force gives , producing the closed form below.
Key Results
- and .
- For , and .
- At constant force of mortality and force of interest , .
- At zero interest, and the APV is the complete expectation of life.
Examples
At and , a continuous benefit rate of 100 per year has APV .
Prerequisites
Related Concepts
- Complete and Curtate Expectation of Life
- Life Annuities Payable Several Times a Year
- Temporary Life Annuity
Sources
- Life Insurance · Lecture 5
Aliases: life annuity payable continuously, continuous temporary annuity, continuous whole life annuity, continuously payable life annuity Keywords: a bar x, A bar x + delta a bar x = 1, 1/(lambda + delta) at constant force, Y = (1 - v^T)/delta, area under the discounted survival curve Symbols: delta, infinity, integral, lambda
Last updated: 27 October 2026 11:52
Continuous Life AnnuityWhole Life Annuity DueForce of MortalityComplete and Curtate Expectation of LifeLife Annuities Payable Several Times a YearTemporary Life Annuity