Mixed Discrete and Continuous Loss Distribution
Definition
A mixed discrete and continuous loss has both positive point masses and an absolutely continuous component. Its distribution can be written , where and .
Interpretation
A claim can be zero, a normal positive amount, or exactly a policy cap. Jumps of the cumulative distribution function (CDF) record point masses; the ordinary derivative between jumps records only the continuous component. This is a specific distribution structure, while a mixture describes averaging component laws.
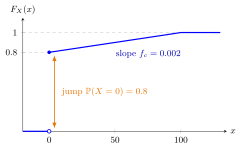
The figure shows the example below. The CDF jumps from 0 to at , and the jump height is the point mass . Between 0 and 100 the CDF rises linearly from to 1 with slope , the continuous component density . No single ordinary density can produce the jump, so both pieces are needed.
A mixture distribution can combine a discrete component and an absolutely continuous component. The component weights give the total atom mass and the total continuous mass; the example mixes a point mass at zero with a uniform positive loss.
Key Results
- .
- when integrable.
- A single ordinary density with respect to length cannot represent the atoms.
- Coverage modifications can introduce atoms even when the original loss is continuous.
Examples
If is zero with probability and otherwise uniform on , its continuous component density is on that interval. The mean is .
Prerequisites
Related Concepts
Sources
- Risk Insurance · Lecture 1
Aliases: mixed loss distribution, loss distribution with atoms, mixed distribution, mixed random variable Keywords: point mass at zero, atom at the policy limit, jump of the CDF, P(X = a) = F(a) - F(a-), continuous component density Symbols: element of, integral, sum
Last updated: 16 October 2026 22:28
Mixed Discrete and Continuous Loss DistributionPoint MassAbsolutely Continuous DistributionMixture DistributionCumulative Distribution FunctionOrdinary DeductiblePolicy LimitFranchise DeductibleIndividual Risk Model