Variance Premium Principle
Definition
For a loss with finite second moment, the variance principle is , with fixed coefficient . The coefficient has units inverse to those of the monetary loss.
Interpretation
The loading increases with squared dispersion. Changing the monetary unit requires a corresponding change in the numerical loading coefficient if prices are to describe the same contract.
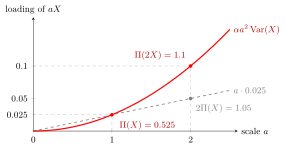
The figure plots the loading for the Examples loss. At it meets the proportional line , giving ; at the parabola reaches 0.1, twice the proportional 0.05, so rather than . This quadratic growth is why the principle is not proportional for fixed .
Variance and standard deviation supplies the squared-dispersion measure used in the loading. For independent losses these variances add, explaining additivity; multiplying all losses by multiplies this loading by .
Key Results
- The principle has nonnegative loading and translation consistency.
- It is additive for independent losses because their variances add.
- It is not proportional for fixed : .
- It preserves equal-mean convex order, but need not preserve stochastic order when means differ.
- Covariance matters when pricing a dependent portfolio.
Examples
For , a Bernoulli loss with probability has premium . Doubling the loss gives premium , not .
Prerequisites
Related Concepts
- Standard Deviation Premium Principle
- Convex Order and More Dangerous Risks
- Expected Value Premium Principle
Sources
- Risk Insurance · Lecture 12
Aliases: variance loading principle, variance principle Keywords: Π(X) = E[X] + α Var(X), not proportional, additive for independent risks, variance loading Symbols: alpha, pi
Last updated: 14 October 2026 08:21
Variance Premium PrinciplePremium Principles and Their PropertiesVariance and Standard DeviationStandard Deviation Premium PrincipleConvex Order and More Dangerous RisksExpected Value Premium Principle