Collective Risk Model
Definition
The collective risk model writes , where is a nonnegative integer claim count and the claim severities are independent, identically distributed nonnegative variables, independent of . The sum is zero when .
Interpretation
The number of claims is random, and the summands describe actual claims rather than all policies. A policy can generate more than one claim unless the frequency model rules that out.
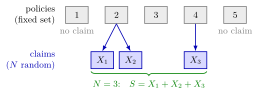
The figure shows one year of a small portfolio. The policies form a fixed set, but the model sums over the claims they produce: here policy 2 has two claims, policy 4 has one and policies 1, 3 and 5 have none, so and . In another year could be 0, giving , or exceed the number of policies. In the Example , so the portfolio produces five claims on average.
The individual risk model sums losses over a fixed set of policies; here the summation is over a random number of actual claims. Assuming i.i.d. random variables gives all severities the same law. The independent random variables assumptions ensure that fixing leaves a sum of independent draws from that law.
Key Results
- Conditional on , total loss has the distribution of a sum of severities.
- Mean and variance follow from the random-sum formulas on the compound distribution page.
- If severities are strictly positive, ; otherwise zero severities also matter.
- Frequency–severity independence is a substantive modelling assumption.
Examples
With and independent severities of mean 100 and variance 400, mean aggregate loss is 500 and variance is .
Prerequisites
- Individual Risk Model
- Independent Random Variables
- Independent and Identically Distributed Random Variables
Related Concepts
Sources
- Risk Insurance · Lecture 3
Aliases: frequency-severity model, random-claim-count aggregate loss, collective model Keywords: S = X_1 + ... + X_N, claim count and claim severity, aggregate loss, frequency–severity independence, P(S = 0) = P(N = 0) Symbols: sum
Last updated: 16 October 2026 22:28
Collective Risk ModelCompound Risk DistributionMaximum Claim in a PortfolioIndividual Risk ModelIndependent Random VariablesIndependent and Identically Distributed Random VariablesCompound Poisson Distribution