System of Linear Difference Equations
Definition
A system of linear difference equations (first order, constant coefficients) is
where is the state vector, is a fixed real matrix and is a given sequence of forcing vectors. It is homogeneous if for all . For every initial vector the unique solution is
Interpretation
Entry says how much variable today contributes to variable in the next period. The system is the vector form of the first-order linear difference equation: the number becomes the matrix , and becomes the matrix power .
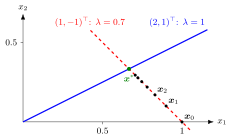
The figure plots the population-shares example below. Writing in the eigenvector basis, the component along () never changes, while the component along () is multiplied by each period. So the iterates move along the dashed line through in direction , with steps shrinking by the factor , towards on the blue eigenvector line.
Drag or change the entries of : in eigenvector coordinates each component is multiplied by its own eigenvalue every period. With the default matrix the component for dies out and the iterates settle on the eigenvector line of .
Powers of are hard to read off directly, which is where eigenvalues and eigenvectors come in. If , then : along an eigenvector the system behaves like a scalar equation. When has independent eigenvectors, write in that basis and each component evolves separately. This is diagonalization applied to dynamics.
Any scalar higher-order equation can be written as such a system with a companion matrix, so the system covers every linear constant-coefficient difference equation. A common mistake is to compute entrywise, as if ; this is only true for diagonal matrices.
Key Results
- If with , then and the homogeneous solution is with .
- For a nondiagonalizable , the Jordan normal form adds terms () for the size of the Jordan block.
- With constant forcing , an equilibrium solves ; it is unique if and only if is not an eigenvalue of . Then .
- Nonreal eigenvalues of the real matrix come in conjugate pairs and produce oscillating real solutions.
- The long-run behaviour is governed by the eigenvalues of largest modulus; see stability.
Examples
Diagonalizable system. Let , with eigenvalues and eigenvectors , . For ,
Check: .
Population shares. Each period of region 1 moves to region 2 and of region 2 moves to region 1: . The eigenvalues are (eigenvector ) and (eigenvector ). From ,
Check: both ways. This is a two-state Markov chain written for column vectors.
Prerequisites
Related Concepts
- Stability of a System of Linear Difference Equations
- Higher-Order Linear Difference Equation
- System of Differential Equations
- Jordan Normal Form
- Markov Chain
Sources
- Math V: Advanced Linear Algebra · Week 2
Aliases: linear system of difference equations, vector difference equation, linear discrete-time system, discrete-time linear system Keywords: x_{t+1} = A x_t + b_t, x_t = A^t x_0, A^t = P D^t P^{-1}, equilibrium (I - A) x* = b, eigenvector decomposition of the solution Symbols: element of, lambda, real numbers, sum
Last updated: 22 October 2026 19:04
System of Linear Difference EquationsStability of a System of Linear Difference EquationsFirst-Order Linear Difference EquationMatrix ProductEigenvalue and EigenvectorDiagonalizationHigher-Order Linear Difference EquationSystem of Differential EquationsJordan Normal FormMarkov Chain