Characteristic Equation for a Differential Equation
Definition
Consider the homogeneous linear differential equation with constant real coefficients
where and is the -th derivative. Its characteristic polynomial is
and is its characteristic equation. The equation is obtained by substituting the trial solution : since , the left-hand side becomes , which vanishes for all if and only if . For a second-order differential equation the characteristic equation is .
Interpretation
The substitution turns a differential equation into an algebraic one: each root of the polynomial gives an exponential "mode" of the exponential function. Writing the equation as a first-order system with a companion matrix, is exactly the characteristic polynomial of that matrix, so the roots are its eigenvalues.
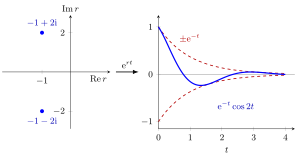
The figure follows the complex-roots example . Its characteristic equation has the roots , marked on the left in the complex plane. Through and Euler's formula they give the real mode on the right: the real part fixes the shrinking envelope , and the imaginary part fixes how fast the solution oscillates inside it.
Move and across : two real roots give two exponentials, a repeated root needs the extra factor , and a complex pair gives .
The discrete-time analogue is the characteristic polynomial for a difference equation, where the trial solution is instead of . The two are linked by : sampling at integer times gives .
Common errors: forgetting that a repeated root needs the extra factor ; writing as the final real answer instead of converting it with Euler's formula; and applying the method to equations with non-constant coefficients, where is generally not a solution.
Key Results
- By the fundamental theorem of algebra, has complex roots counted with multiplicity.
- A real root of multiplicity gives the solutions .
- Since the coefficients are real, nonreal roots come in pairs () by the complex conjugate root theorem. Each pair gives the real solutions and , because ; a pair of multiplicity gives these two functions multiplied by .
- The functions obtained this way form a basis of the solution space, so the general solution is their linear combination.
- For , has discriminant : positive gives two real roots, zero a double root , negative a complex pair .
Examples
Distinct real roots. : , so .
Complex roots. : , so , a damped oscillation.
Double root, checked. : . For : , , and .
Triple root. : , so .
Prerequisites
Related Concepts
- General Solution of a Linear ODE
- Stability of Solutions of Higher-Order ODEs
- Characteristic Polynomial for a Difference Equation
- Characteristic Polynomial
Sources
- Math V: Advanced Linear Algebra · Week 4
Aliases: auxiliary equation, characteristic polynomial of an ODE, characteristic equation of a linear ODE Keywords: e^{rt}, characteristic roots, repeated root, complex roots, e^{alpha t} cos(beta t) Symbols: alpha, beta, lambda, square root
Last updated: 22 October 2026 19:04
Characteristic Equation for a Differential EquationGeneral Solution of a Linear ODEParticular Solution of an Inhomogeneous Linear ODEStability of Solutions of Higher-Order ODEsSecond-Order Differential EquationRoot of a PolynomialExponential FunctionEuler's FormulaCharacteristic Polynomial for a Difference EquationCharacteristic Polynomial