Whole Life Annuity Due
Definition
A unit annual whole life annuity-due pays at the beginning of each year while the life aged is alive, including a certain payment at issue. Its present value is and actuarial present value (APV) is .
Interpretation
Each annual payment is a pure endowment for its payment date. A longer lifetime increases the number of payments, whereas a death benefit is generally discounted more heavily when death occurs later.
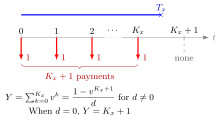
For a fixed lifetime the annuity-due is no longer random: payments are made at while the life is alive, and the payment that would be due at falls after death at . These payments form an annuity certain, so . For this is , and when finite. At zero interest, and when finite.
Change and : each arrow is the expected present value of the payment at , and throughout. At and , and .
For a realized curtate future lifetime , the payments at have the same discounted sum as an annuity certain with payments; its geometric-sum formula gives when ; at the sum is . To average over possible lifetimes, write each payment using an indicator random variable: the payment at time is made only on survival to . Its expected discounted value is , so adding these expectations gives the APV sum below.
Key Results
- .
- For , , so , where is the APV of whole life insurance with annual settlement.
- For , when finite; at , and when finite.
- One-year recursion: when ; if , then .
Examples
If and , the unit annuity APV is . This uses annual death settlement for .
Prerequisites
Related Concepts
- Whole Life Annuity Immediate
- Temporary Life Annuity
- Continuous Life Annuity
- Variance of an Insurance Present Value
- Life Insurance Valuation Recursions
Sources
- Life Insurance · Lecture 5
Aliases: annual life annuity in advance, whole-life annuity-due, life annuity-due, life annuity in advance Keywords: ä x, A x + d ä x = 1, payments in advance while alive, ä x = 1 + v p x ä x+1 Symbols: infinity, sum
Last updated: 27 October 2026 11:52
Whole Life Annuity DueContinuous Life AnnuityDeferred Life AnnuityLife Annuities Payable Several Times a YearEquivalence Principle for Life Insurance PremiumsTemporary Life AnnuityVarying Life Annuity PaymentsWhole Life Annuity ImmediateAnnuity CertainPure EndowmentCurtate Future LifetimeIndicator Random VariableVariance of an Insurance Present ValueLife Insurance Valuation Recursions