Death Benefits Payable at Fractional-Year Boundaries
Definition
A unit death benefit payable at the end of the -year interval of death is paid at , for a positive integer . Its actuarial present value (APV) is . Mortality is continuous, so death exactly on a payment boundary has probability zero.
Interpretation
Settlement at frequency leaves a waiting time of less than year after death. Refining to a frequency that is an integer multiple of cannot increase the waiting time for any death. An arbitrary higher frequency need not reduce every realized wait because its calendar grid may not contain the earlier grid. Unlike an annuity payable times a year, this is one benefit payment, not instalments of .
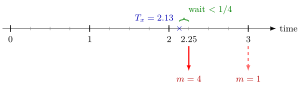
The figure shows the example with death at . With quarterly settlement the benefit is paid at the next quarter-year mark, , so the wait is less than year; with annual settlement it is paid at the end of the year of death, time 3.
Move and drag the probe : the benefit waits until the next -year mark, so converges to as for nonnegative interest. For positive interest it is nondecreasing along nested refinements, when each new frequency is an integer multiple of the preceding one; arbitrary increases in need not be monotone. With , a death at is paid at .
Whole life insurance provides the same death benefit with either annual or immediate settlement. The fractional-year version changes the settlement grid. Under uniform distribution of deaths (UDD), the fraction of the year lived is uniform and independent of the year of death, allowing within-year discounting to be averaged separately.
Key Results
- .
- As , for nonnegative interest.
- Under UDD in each year and , , where .
- For , the continuous limit is under UDD, with . At , timing does not change the present value of the unit death benefit.
Examples
For quarterly settlement (), death at leads to payment at time 2.25. Annual settlement would pay at time 3.
Prerequisites
Related Concepts
Sources
- Life Insurance · Lecture 3
Aliases: m-thly death benefit, insurance settlement frequency, m-thly insurance, fractional-year settlement of death benefits Keywords: A x (m), i over i(m) under UDD, A bar x = (i/delta) A x, quarterly settlement, monthly settlement Symbols: delta, infinity, sum, tau
Last updated: 27 October 2026 11:52
Death Benefits Payable at Fractional-Year BoundariesWhole Life InsuranceUniform Distribution of DeathsLife Annuities Payable Several Times a YearInterest and Discounting