Whole Life Insurance
Definition
A unit whole life insurance pays on death whenever it occurs. For immediate payment its present value is and actuarial present value (APV) is . For payment at the end of the year of death, and APV is , where .
Interpretation
The contract covers the entire remaining lifetime. Its value depends on whether settlement occurs at death or later at an annual boundary.
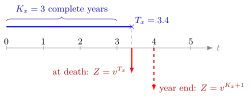
The figure follows one illustrative lifetime with death at , so complete years are lived. Immediate settlement pays at the moment of death, with present value ; annual settlement waits until the end of the year of death, , with . Since for every lifetime, the immediate payment is never later, which is why when interest is nonnegative.
Change and : is the red area under . Drag the probe along , and switch on end-of-year settlement () to see . The displayed window is finite; compare its shown contribution with the full lifetime value and omitted tail in the readout.
The curtate future lifetime determines the annual settlement date . For immediate settlement, the force of mortality converts the survival probability into the death density used in the APV integral.
Key Results
- .
- .
- For nonnegative interest, because immediate settlement is earlier.
- At constant force of mortality and force of interest , .
Examples
With and , a benefit of 100 paid at death has APV .
Prerequisites
Related Concepts
Sources
- Life Insurance · Lecture 3
Aliases: whole-life assurance, insurance payable at death, whole of life insurance, whole of life assurance Keywords: A bar x, A x with end-of-year settlement, v^(K+1), lambda/(lambda + delta) at constant force, payable whenever death occurs Symbols: delta, infinity, integral, lambda, mu, sum
Last updated: 27 October 2026 11:52
Whole Life InsuranceDeferred Life InsuranceDeath Benefits Payable at Fractional-Year BoundariesLife Insurance Valuation RecursionsTerm Life InsuranceVarying Life Insurance BenefitsActuarial Present ValueForce of MortalityCurtate Future LifetimeSelect and Ultimate Mortality